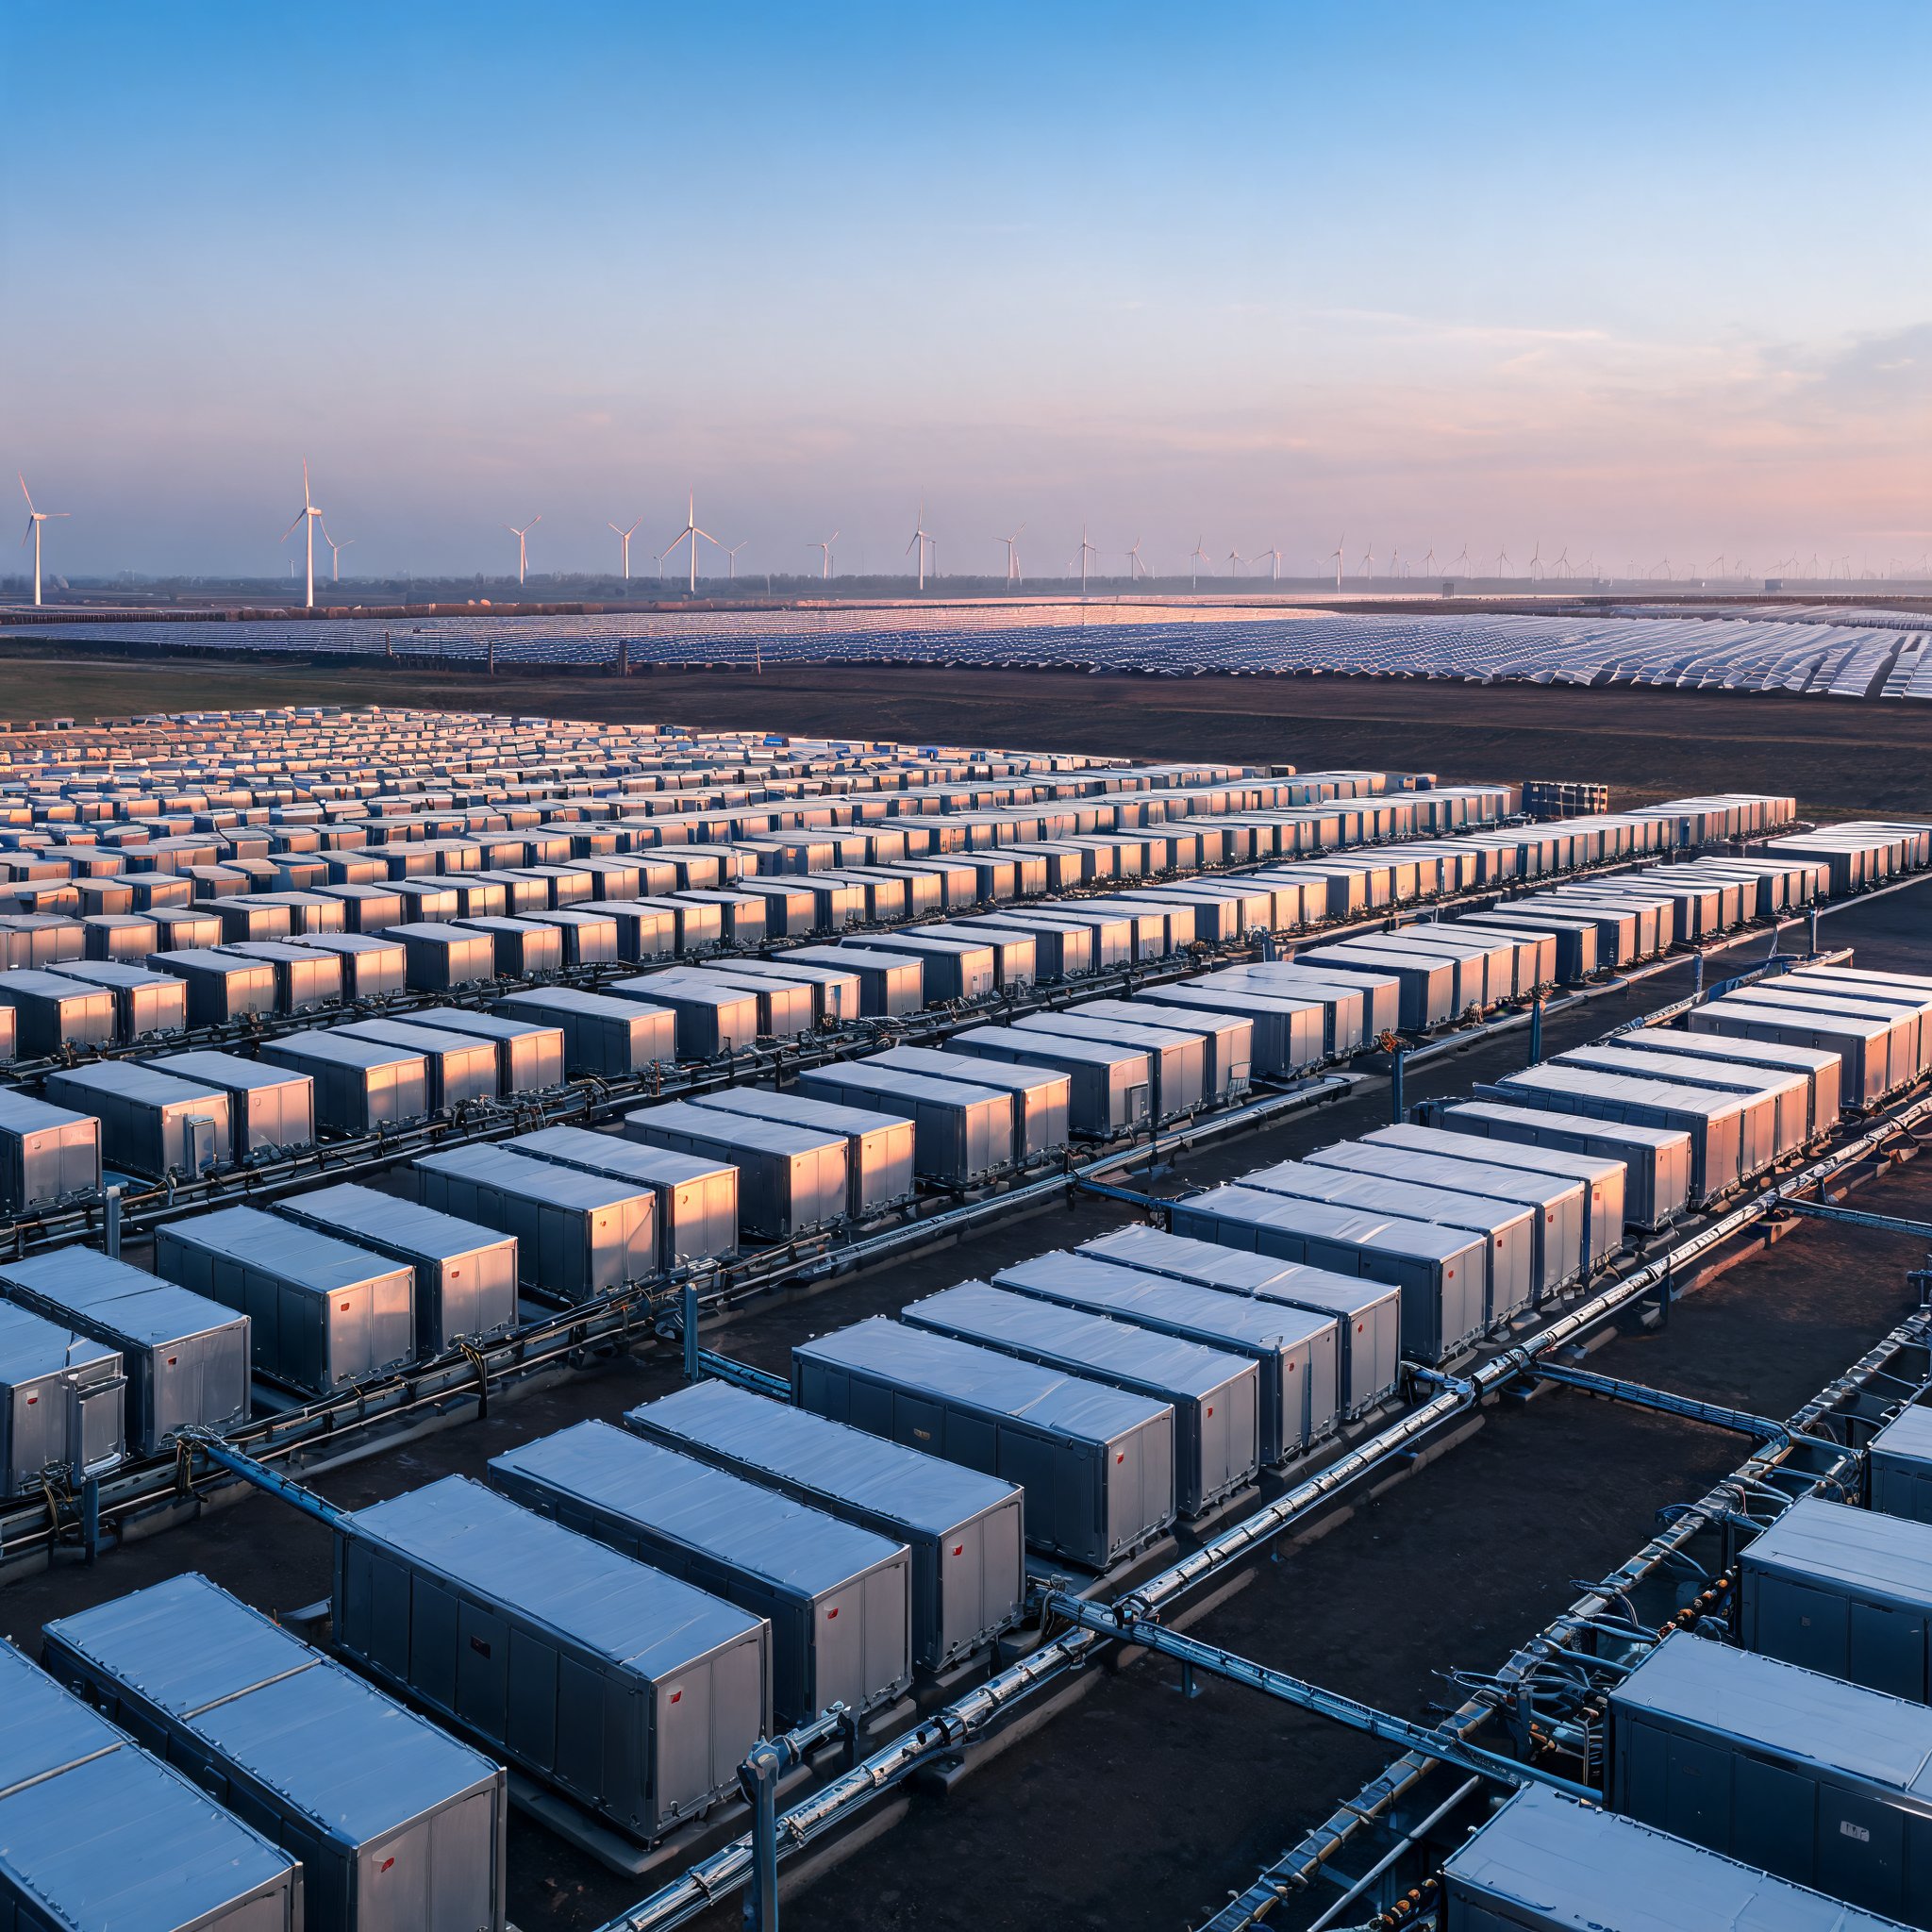
China's operational new-type energy storage fleet stood at 167 GW/435 GWh at the end of September 2026, 63% above the level a year earlier, according to figures the National Energy Administration (NEA) released on October 30.
The statistics were presented at the agency's quarterly press conference on national energy development. The new-type category covers electrochemical systems, compressed-air plants and other emerging technologies, but excludes conventional pumped hydro.
Measured against 135.93 GW/351.12 GWh recorded at the end of 2025, the September total represents a net addition of roughly 31 GW/84 GWh over the first nine months of 2026.
Longer duration, more operating hours
Average storage duration rose to 2.61 hours, about 0.27 hours more than a year earlier, the NEA said. Equivalent utilization hours over the nine-month period reached roughly 915, some 10 hours above the same stretch of 2025.
According to the agency, these gains indicate changes in how systems are configured and operated, rather than growth in installed capacity alone.
The NEA attributed the expansion to government policy, technological innovation, domestic industrial supply chains and rising demand for flexibility in the power system.
Renewables build the case for flexibility
Combined wind and solar generating capacity passed 2.01 TW at the end of September, accounting for about 48.7% of China's total installed power capacity. As output from variable sources expands, storage is used to absorb surplus electricity, shift generation into higher-demand periods and provide fast-response grid services.
A market tilting toward independent and larger projects
Official 2025 figures showed independent storage facilities at 51.2% of cumulative new-type installations. Projects rated at 100 MW or more represented 72% of installed capacity, while systems with durations of at least four hours accounted for 27.6%.
Lithium-ion batteries remain dominant at approximately 96% of installed new-type capacity, while compressed-air, flow batteries and other technologies are gradually gaining ground.
Market reforms are expected to reinforce these patterns. China has been developing arrangements under which independent storage operators earn revenue from electricity trading, ancillary services and capacity remuneration, gradually reducing reliance on the mandatory storage requirements attached to renewable projects.
2030 target and a provincial example
The 15th Five-Year Plan for power system development targets 300 GW of new-type storage by 2030, with greater emphasis on longer-duration systems, grid-forming capabilities and improved operational efficiency.
Storage's contribution is already visible in renewable-rich regional grids. In western Inner Mongolia, the grid operator reported 20.23 GW/70.47 GWh of operational storage capacity in October; during emergency dispatch, the fleet supplied up to 12.25 GW, equivalent to 33% of the grid's electricity demand at that moment.
Such examples illustrate how storage can provide substantial short-term balancing capacity in systems with high renewable penetration. For other countries expanding wind and solar generation, China's deployment offers experience in large-scale storage manufacturing, grid integration and centralized dispatch.